Protecting the people behind the business.

Most businesses insure their premises, vehicles and equipment. Far fewer protect the people the business actually depends on.

A company's value rarely sits in its furniture. It sits in the skills, relationships and judgement of a few key people. Business protection is about making sure the business, and the families behind it, are looked after if one of those people dies or becomes seriously ill.

Campden Brook advises on relevant life cover. Please be aware that Campden Brook are not authorised to provide advice on other forms of Business Protection, such as Key Person and Shareholder Protection. These will be referred to a trusted third party adviser.

Relevant life cover

Life cover for a director or employee, owned and paid for by the company. If the person covered dies during the policy, the payout goes through a trust to their family or other beneficiaries, not to the business.

Premiums are usually treated as a business expense, provided HMRC accepts they're paid wholly and exclusively for the purposes of the business, and they're not normally treated as a benefit in kind. Tax treatment depends on individual circumstances and may change in future.

A relevant life policy has no cash-in value at any time. If premiums stop, the cover stops.

Advised by Campden Brook
Key person cover

Pays a lump sum to the business if someone it depends on dies or is diagnosed with a serious illness. The money can help replace lost profit, reassure lenders and suppliers, and pay for recruiting and training a replacement.

Please be aware that Campden Brook are not authorised to provide advice on Business Protection, this will be referred to a trusted third party adviser.

Through our specialist network

Shareholder and partnership protection

If a co-owner dies, their shares usually pass to their family, who may not want to be involved in the business. Shareholder protection, alongside a legal agreement drawn up by your own solicitor, can provide the money for the remaining owners to buy those shares at a fair value.

Please be aware that Campden Brook are not authorised to provide advice on Business Protection, this will be referred to a trusted third party adviser.

Through our specialist network

Management liability

Directors and officers can be held personally responsible for decisions made on behalf of their company. Management liability insurance can cover the cost of defending claims and investigations.

We don't advise on management liability ourselves. We can introduce you to a specialist commercial insurance broker.

Through our specialist network

Could relevant life suit you?

  • You're a director or employee of a limited company
  • You don't have death-in-service cover through a group scheme
  • You'd rather the business paid for cover than pay from your own taxed income
  • You want any payout to go to your family, not the business

If most of those sound familiar, it's worth a conversation. Relevant life isn't available to sole traders. We'll always suggest you speak to your accountant about the tax position too.

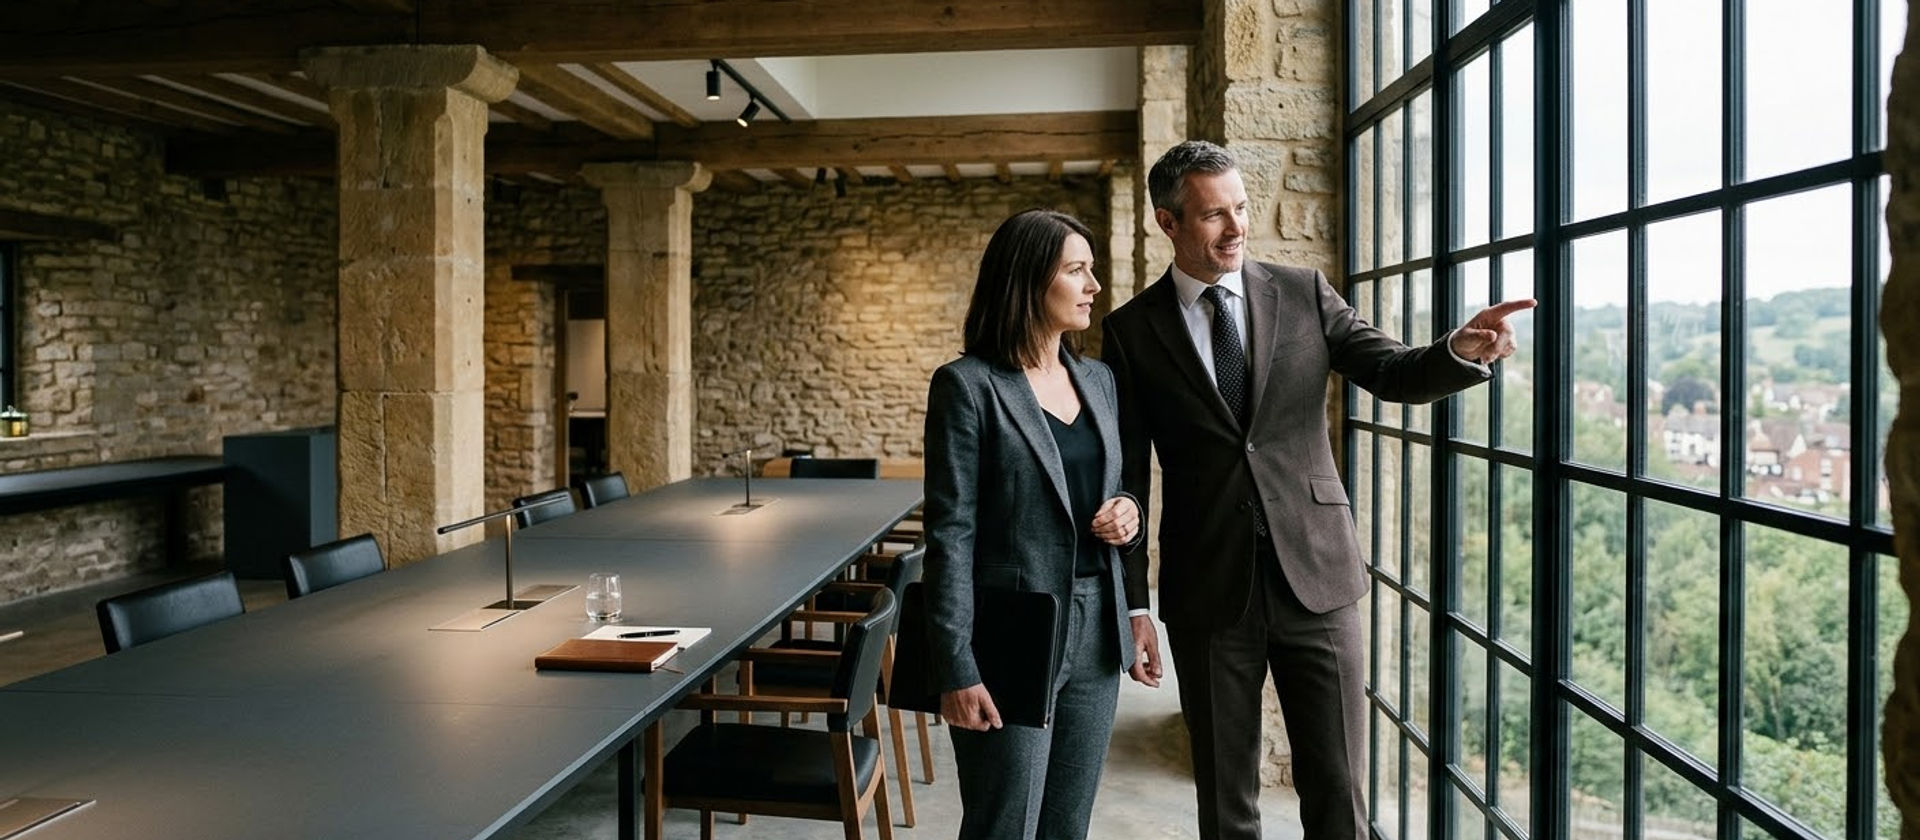
A company director in a converted Cotswold barn office

Business protection questions

How is relevant life different from a personal life policy?

The cover is similar, but the company owns and pays for the policy instead of you paying from your own income after tax. The payout goes through a trust to the people you choose.

What happens to relevant life cover if I leave the company?

The cover is tied to your employment. Some policies can be transferred to a new employer if they agree; otherwise the cover ends. We'll explain how this works for the policy we recommend.

Who will advise me on key person or shareholder protection?

Please be aware that Campden Brook are not authorised to provide advice on Business Protection, this will be referred to a trusted third party adviser.

We'll make the introduction and stay in touch, so you're not starting from scratch.

Do I need a solicitor for shareholder protection?

Usually, yes. Shareholder protection normally works alongside a cross-option or similar agreement between the owners, which should be drawn up by your own solicitor.

Talk to us about protecting your business

Tell us a little about your company and what you'd like to protect. We'll come back to you, usually within one working day.

Loading the enquiry form…